
The relocation package that can beat the same cash bonus
An employer can spend the same amount and leave a relocating worker with a very different result. The deciding factor is which costs the package covers.
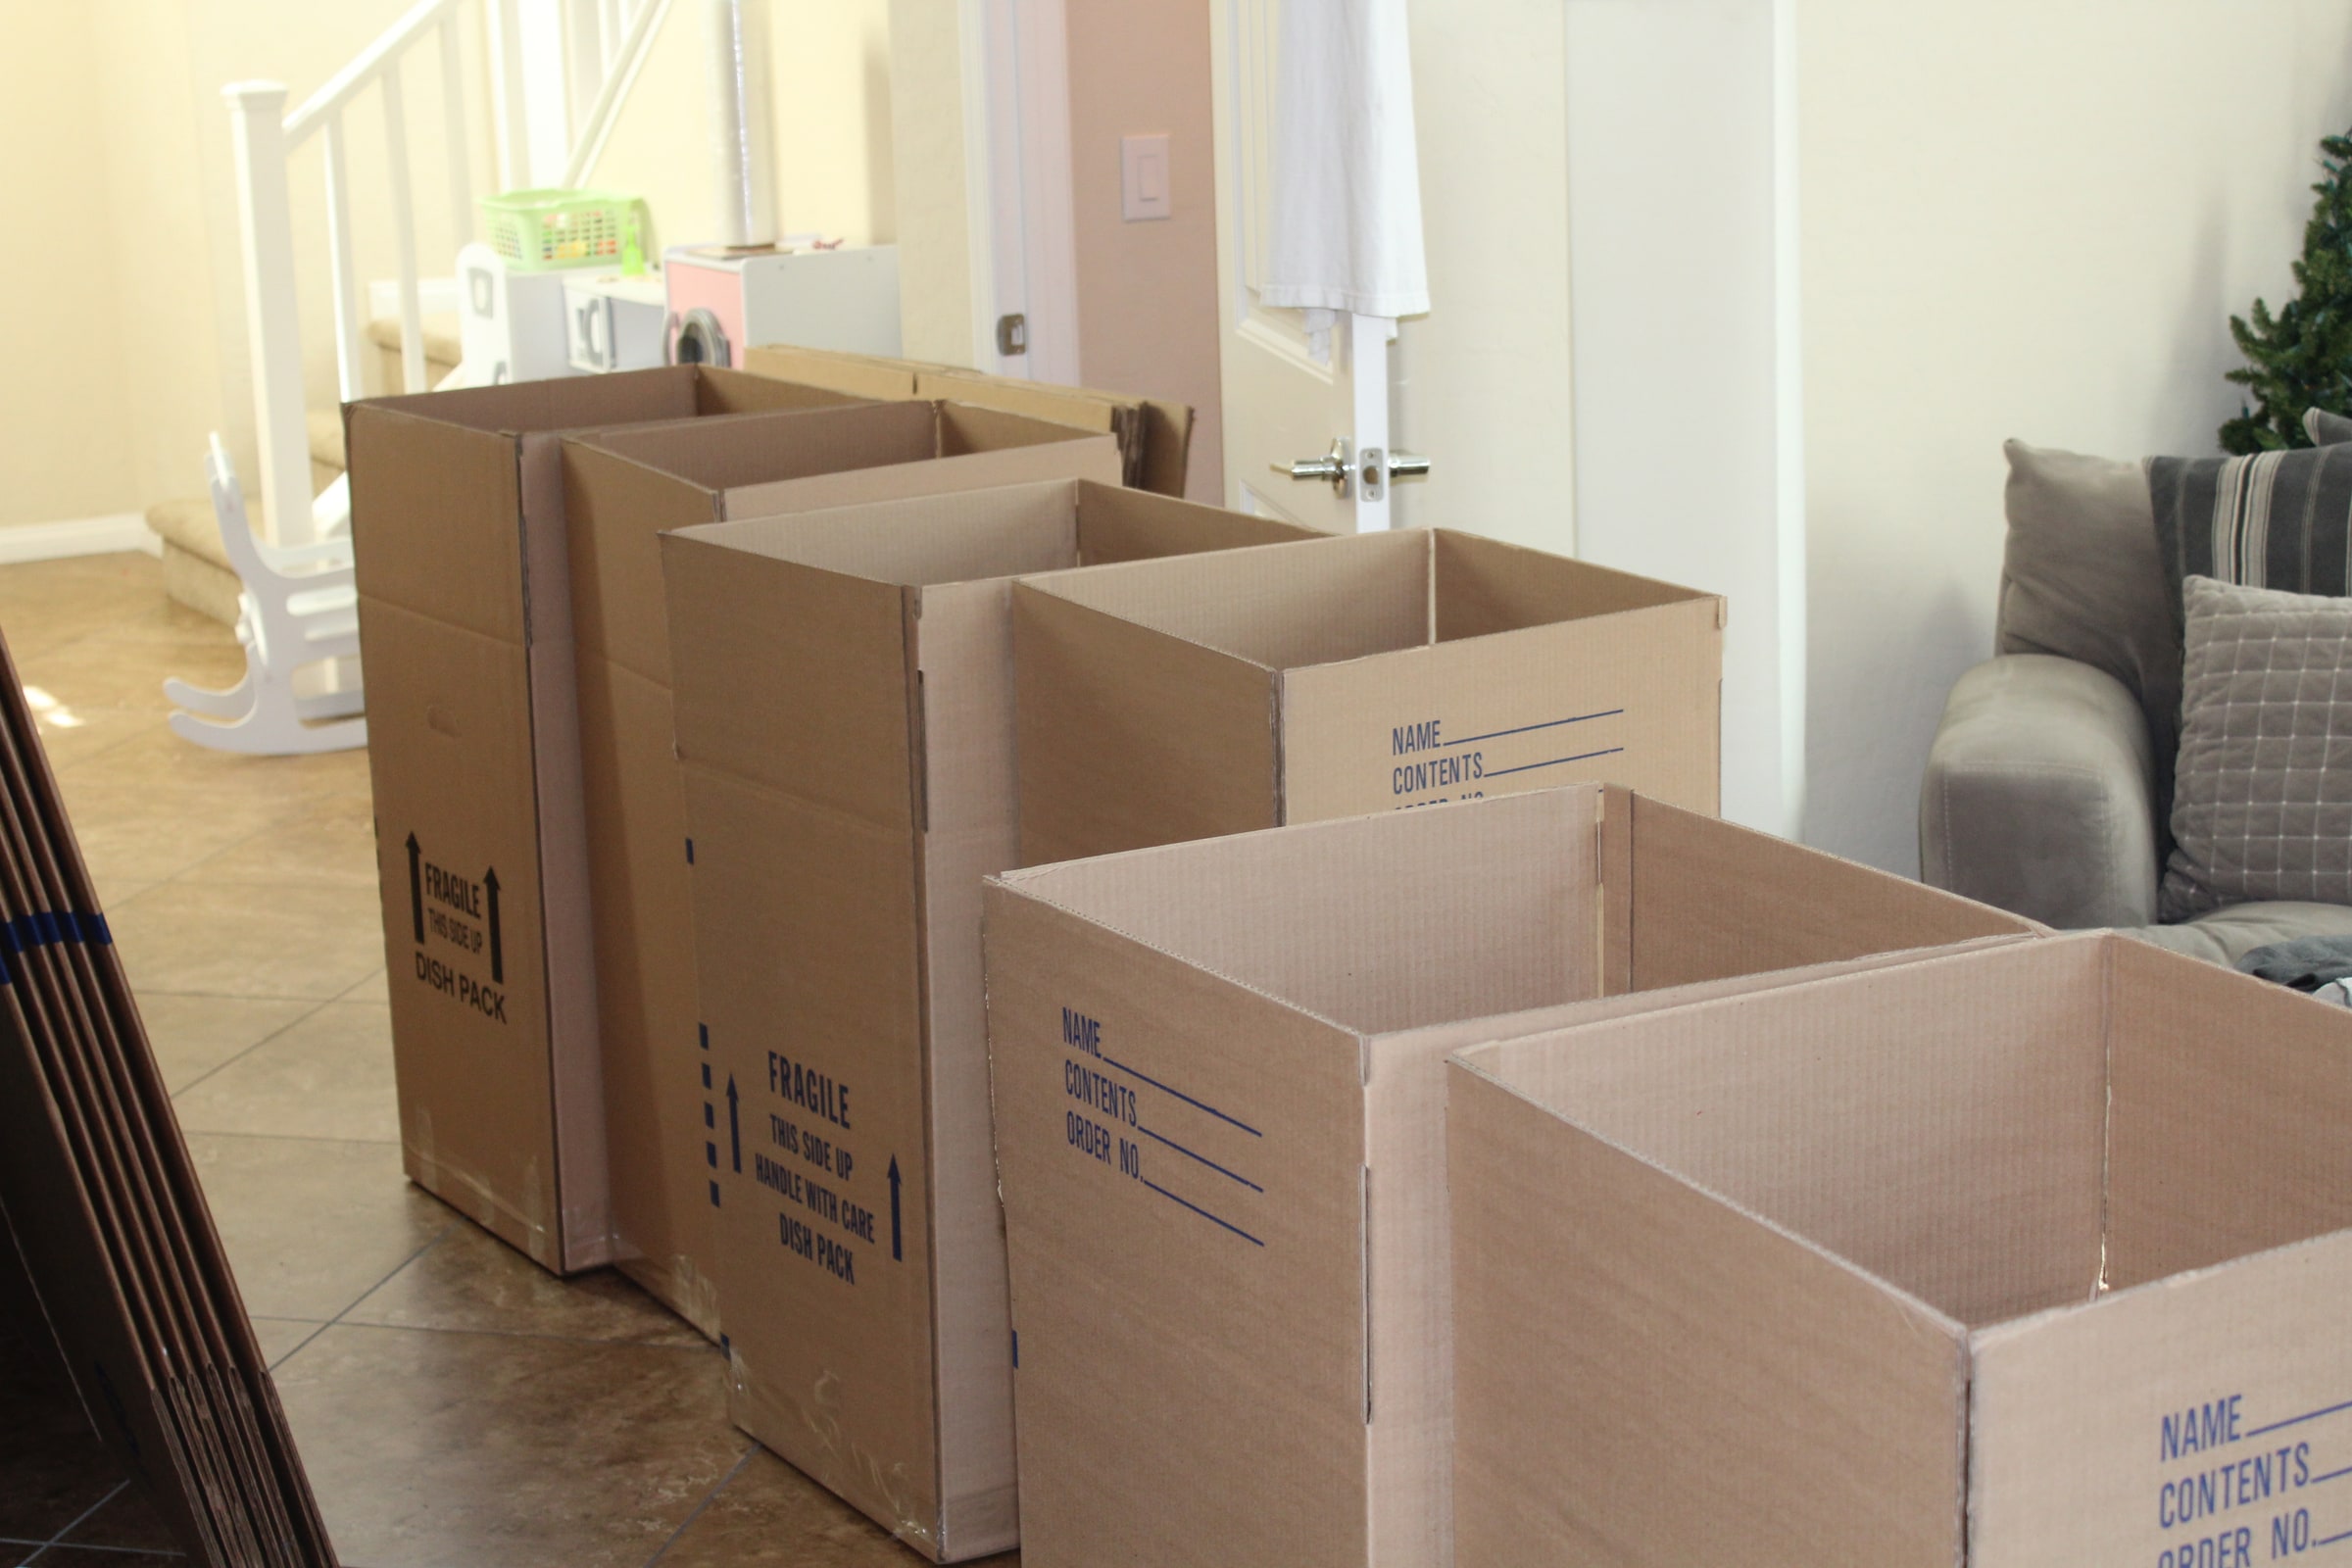
A Swedish employer has SEK 100,000 available to help a new international hire move. The offer can arrive as a cash bonus, reimbursement for the move or a collection of benefits. Those labels may look interchangeable in a negotiation, but Swedish tax and contribution rules treat them differently. Employer contributions, income tax and the legal definition of a moving cost can change how much of the same budget solves the employee's actual problem.
The starting point is unusually useful. Skatteverket guidance says an employer can reimburse moving expenses tax-free when the move is caused by a change in the employee's work location. Qualifying costs include packing, transporting and unpacking household goods, as well as the employee's and family's travel to the new location. The reimbursement should match actual eligible expenditure rather than becoming an unaccounted lump sum.
The exclusions shape the negotiation. The same guidance leaves out double housing, trips back home and losses on the sale of a home. A payment for a private move is taxable. Calling an allowance a relocation payment does not make it exempt if the underlying expense falls outside the rule. Receipts, the work-related reason for the move and the exact cost category therefore matter more than the label used in an offer letter.
A normal cash bonus enters a different calculation. Under contribution rates, the standard full employer contribution is 31.42 percent for the ordinary group covered by that rate. If SEK 100,000 is the employer's total budget, the whole amount cannot become gross salary because the contribution also has to fit inside it. The calculator below uses that total-cost interpretation and lets the reader change the illustrative income-tax rate.
Compare the same employer budget
Illustration only. It assumes the standard 31.42 percent employer contribution rate. Tax-free reimbursement cannot exceed actual qualifying work-related moving costs. Housing, double housing, home trips and home-sale losses are excluded.
With a SEK 100,000 employer budget, full 31.42 percent employer contributions and a 32 percent illustrative tax rate, a cash bonus leaves about SEK 51,743, while reimbursement of SEK 100,000 in qualifying moving costs can cover the full amount.
That comparison is not a promise that every relocating employee can receive SEK 100,000 tax-free. The person must actually incur that much in eligible cost. If eligible invoices total SEK 40,000, the useful tax-free comparison stops at SEK 40,000. The remaining employer budget needs its own treatment. It could become taxable cash or fund another benefit, but it cannot be relabelled as a moving expense without the qualifying expenditure.
Housing is a common trap in relocation packages. Housing rules say free or subsidised housing is generally a taxable benefit and subject to employer contributions. It belongs in a separate line of the offer, with the taxable value made visible, rather than being bundled into the tax-free moving-cost total.
Approved expert tax relief changes the cash side, but not for everyone. The expert relief guide says 25 percent of covered salary is exempt and that certain employer-paid moving costs, two home-country holiday trips per year and children's school fees can be fully exempt. The 2026 threshold is SEK 88,801 a month under the remuneration route, and one-off moving or relocation allowances do not count toward it. Relief must be approved; it should never be assumed in a standard offer.
The practical negotiation is a cost schedule, not a single headline number. Ask the employer to separate qualifying moving invoices, taxable cash, housing and any expert-relief items. Confirm whether the quoted amount is gross salary or the employer's total cost. Then compare usable value under the same assumptions. That makes a relocation package measurable before either side signs it.
DailySweden
DailySweden's desk of editors, reporters, researchers and investigative journalists. We bring readers factual, truthful and objective reporting on the issues that matter to them.